Reverse Mortgages
Will I still own my home with a reverse mortgage?
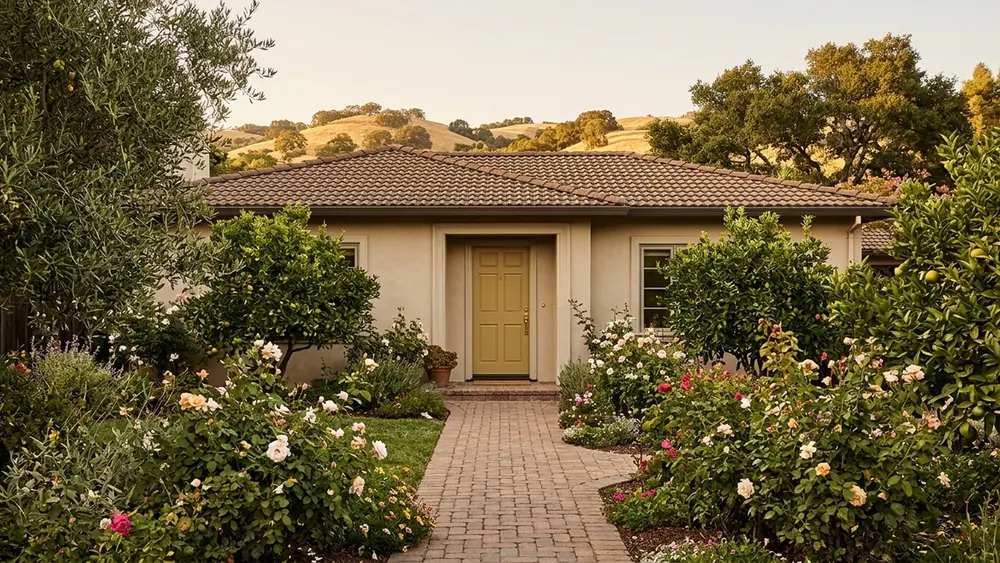
Yes. With a reverse mortgage you keep ownership of your home, and the lender holds a lien against it, as with any mortgage. You also keep the obligations of owning it, which is what keeps the loan in good standing.
On this page
Yes, ownership stays with you
Yes. With a reverse mortgage, you keep ownership of your home. The title stays in your name, and the lender holds a lien against the property, the same way a lender does with any mortgage. You continue to live in the home, make decisions about it and carry the responsibilities that come with owning it. What changes is how your equity is used, not who owns the house.
This is the question that comes up first, and for good reason. Many people have heard that a reverse mortgage means signing the house over to a bank. That is not how it works. A reverse mortgage is a loan against home equity for eligible homeowners, not a sale of the home. The program’s published rules and the official disclosures describe exactly what the lender’s interest in the property is.
It matters because ownership and equity are two different things, and mixing them up leads to the wrong decision in either direction. You can own your home outright and still see your equity shrink over time as a reverse mortgage balance grows. Understanding both ideas, separately and clearly, is what lets you weigh the loan honestly against the other options open to you. A clear view of both is the starting point for every other question in this article.
What the lender holds and what you keep
Think of it in two layers. The first layer is ownership: your name on the title, your right to live in the home, and your responsibility for it. The second layer is the loan: a balance secured by the home, which the lender can look to for repayment when the loan comes due. A reverse mortgage adds to the second layer without taking away the first.
The equity is where the trade off sits. With a regular mortgage, payments reduce the balance and your equity tends to grow as you pay. With a reverse mortgage, you generally make no monthly mortgage payment, and interest and costs are added to the balance instead. So the balance usually grows over time, and the equity left in the home shrinks by the same amount. That is the real cost of the loan.
Because you still own the home, decisions about it remain yours. Questions such as whether you can sell, add someone to the title or move later are reasonable to raise early, and the answers come from the loan terms and the official disclosures. A legal professional or an estate professional can explain how ownership choices interact with your wider plans, and a mortgage professional can explain how the loan fits around them. Write each answer down so it is easy to find later.
Keeping the loan in good standing
Ownership comes with obligations, and those obligations are what keep a reverse mortgage in good standing. You keep paying property taxes, you keep homeowners insurance in place, and you keep the home in reasonable repair. You also continue to live in the home as your primary residence. None of these are new, because every homeowner carries them, but with a reverse mortgage they become part of the loan terms.
If an obligation is not met, the loan can come due sooner than you expected. That is the scenario people worry about when they ask whether they could lose the home, and it is why budgeting for taxes, insurance and upkeep matters so much. Before you sign, map those costs against your monthly income in plain numbers, so you know they fit comfortably rather than hoping they will. A financial professional can help you build that budget if it feels uncertain.
If your circumstances change after the loan closes, the most useful step is an early conversation. Tell the loan servicer, the company that manages the loan, as soon as you see a problem coming, and ask what your options are under the terms. A financial professional can help you rework a budget, and an insurer or insurance agent can explain changes to your coverage. Waiting rarely makes the conversation easier.
Common worries about losing the home
Most worries about reverse mortgages come from a few misunderstandings that get repeated until they sound like facts. Each one has a grain of something real inside it, which is why it is worth separating the myth from the actual rule. Here are the ones that come up most often in conversations with retirees and their families in San Rafael and across California. Each one is easy to check once it is named.
- Believing the lender takes ownership of the home when the loan closes
- Believing heirs automatically lose the home when the borrower passes away
- Believing there are no ongoing costs once the loan is in place
- Believing the loan can never come due while you still live there
The first two are generally not how the loan works, and the last two are where surprises tend to come from. Ownership stays with you, and heirs usually have choices when the loan comes due. But taxes, insurance and upkeep continue, and the loan terms describe when the balance must be repaid. The counselor and the official disclosures are the place to confirm each point for your own loan.
Questions to settle before you sign
Ownership questions are easiest to answer before the loan closes, while you can still change course. Each question below has a clear owner, someone whose role is to answer it for your situation. Keeping the questions separate also stops one general opinion from standing in for an answer that should come from the right source. Use this table as a simple way to track who answers what.
| Question | Why it matters | Who to ask |
|---|---|---|
| Whose name stays on the title | Confirms who owns the home after closing | Title or escrow company |
| What obligations keep the loan in good standing | Missing one can make the loan come due | Counselor and official disclosures |
| How the balance could change over time | Shows how much equity may remain | A mortgage professional |
| What happens for heirs when the loan ends | Shapes the family plan for the home | An estate professional |
| Whether any benefits or taxes are affected | Prevents an unwelcome surprise later | A tax or financial professional |
Keep notes on who answered each question and when, and keep them with the loan paperwork. Rules and circumstances can change, so an earlier answer may need checking again before you commit. Your official disclosures show the final terms in writing, and it is worth reading them line by line against your notes so nothing in them catches you off guard. If anything differs, ask before you sign.
What happens for your heirs
When the loan comes due, usually when the home is sold or is no longer the borrower’s primary residence, the balance is repaid. Heirs generally have choices at that point, such as repaying the balance to keep the home or selling it and using the proceeds to repay the loan. The exact options and timing depend on the loan terms, which the official disclosures and the counselor explain. Ask how much time heirs would have to decide, and where that is written.
This is why family conversations belong at the start, not the end. Share your goals, the costs and the alternatives openly, and include anyone who may inherit the home. Questions about wills, trusts and how the home passes to heirs are for an estate professional or a legal professional. Having those answers in hand lets your family see the full plan, rather than piecing it together later under pressure.
Getting ready to talk it through
A first conversation goes further when you bring a few things with you. None of it needs to be perfect or complete. The point is to give whoever you talk with enough real information to explain how a reverse mortgage would work on your home, rather than in general terms. Here is a simple list to start with, and you can add to it as questions come up.
- A recent mortgage statement, if you still have a loan on the home
- Your property tax and homeowners insurance information for the current period
- A short outline of your monthly income and regular expenses
- The names of family members or professionals you want involved
With those in hand, the conversation can focus on your questions instead of on paperwork. If you would like a patient walk through how ownership, equity and obligations fit together, Scott Baer works with retirees across California and starts with the plain numbers, not a pitch. Which part of keeping your home matters most to you as you weigh this decision? There is no pressure to decide in a first conversation.
This article provides general information about real estate financing in California. It is not a loan offer, pre-approval, commitment to lend, or personalized legal, tax, or financial advice. Programs, availability, terms, and eligibility requirements vary by lender, property, and borrower and may change. Review the disclosures and loan documents applicable to your transaction and consult a qualified professional for tax, legal, or estate-planning guidance.
Scott Baer, Mortgage Broker and Loan Originator | NMLS #218304 | CA DRE #01103412
California Mortgage Advisors, Inc. | NMLS #1825 | CA DRE #01170868
Licensed by the California Department of Real Estate.
Equal Housing Opportunity
Written by