Investor and Multifamily Loans
How is financing a rental different from a primary home?
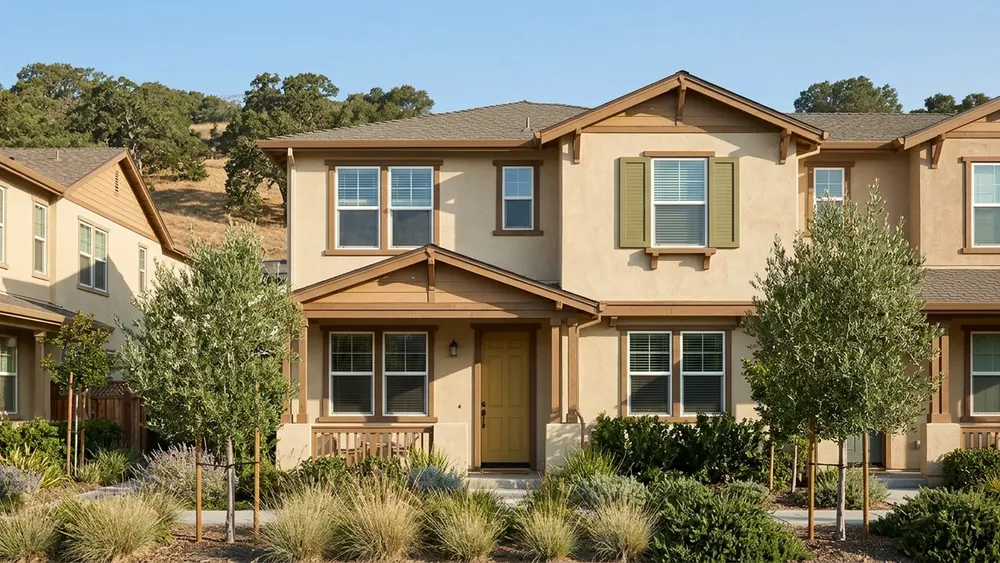
A rental loan is reviewed differently from a home you live in. Lenders often look at rental income, reserves and your down payment in their own way, so the terms and the paperwork can differ. Compare both before you commit.
On this page
The short answer on rental financing
Financing a rental is different from financing a home you live in because the lender is weighing a different kind of risk. On an investment property, lenders often look at rental income, reserves and your down payment differently than they would for a primary home. The terms, the paperwork and the questions you are asked can all change, even when the borrower and the house look the same on paper. The rest of this guide walks through those differences one decision at a time.
This matters because many owners assume the loan they used for their own home will work the same way on a rental. It often does not. If you plan a purchase in California around the experience of buying your own home, the differences can show up late, when there is less time to adjust the plan or the budget. Knowing them early lets you compare options calmly.
None of this means a rental is harder or easier to finance in general. It means the review asks different questions. The useful step is to see how each loan option would treat your particular property and your particular plan, side by side, before you commit to a purchase. That way the decision rests on your own numbers rather than on what worked for a friend or a relative. It also gives you time to adjust the plan if the numbers point somewhere you did not expect.
What lenders tend to review on rentals
On a primary home, the review centers on you: your income, your debts, your credit and the cash you bring. On a rental, the property itself becomes part of the story. A lender may want to understand how the property is expected to earn income and what happens to your finances if it sits empty for a while. Knowing the areas in advance means you can prepare for them instead of reacting. Here are the areas that commonly get a closer look.
- How the property’s rental income is documented and how much of it is counted
- The reserves you hold after closing to cover payments if a unit sits empty
- The size of your down payment, which can be weighed differently on investment property
- Your other properties, their loans and how those obligations fit with your income
Records worth gathering before you apply
Because the property matters more on a rental loan, the paperwork usually reaches beyond your own pay records. Gathering it early saves back and forth later, and it shows quickly whether anything needs an explanation. Not every item applies to every borrower, and your mortgage professional can tell you which ones matter for your situation. These are the records that most often come up.
- Current leases for any units that are already rented to tenants
- Records of rent actually collected, such as bank deposits for the property
- Property expense records, including insurance, property taxes, repairs and any association dues
- Tax returns that show how rental income has been reported in past years
- A list of every property you own, with its current loan and payment
How rental income gets counted
One of the most common questions is how rental income is counted. Owners often expect the full rent to be added to their income, and that is not always how it works. Lenders often apply their own method, which may count only part of the rent or count it after expenses, to allow for vacancies and upkeep. The method depends on the program and on how the income is documented.
Whether a property is already rented also matters. A rental with an existing lease and a record of rent collected tells a different story than a property you plan to rent after closing. In the second case, a lender may rely on an estimate of market rent, often from the appraisal, rather than on actual history. Ask how each option would treat your property before you build a budget around the rent. Two similar properties can be read very differently depending on their rental history.
This is where plain numbers help. Write down the rent you expect, then write down what a lender might actually count, and look at the gap. If the purchase only works when every unit is rented and every expense stays low, that is worth knowing before you make an offer. A tax professional can tell you how the rental income affects your own tax picture, which is a separate question from the loan itself.
Why the down payment and reserves matter
On a home you live in, the down payment mostly shapes your loan amount and monthly payment. On a rental, it can also shape which programs are available and how the loan is priced. Requirements vary by program and change over time, so treat anything you have heard secondhand as a starting point. The official loan disclosures, including the Loan Estimate, are where the actual terms appear in writing. Compare them across options line by line, so a difference in down payment or pricing does not hide behind a similar monthly payment.
Reserves deserve the same attention. These are funds you still have after closing, set aside to cover payments if a tenant leaves or a repair comes up. Lenders often look at reserves more closely on investment property, because the property’s income can rise and fall from month to month. Planning for them early keeps the purchase from draining every dollar you have, which leaves room to handle the ordinary surprises of owning a rental.
Before you fall for the rent a property could earn, look at what happens to your budget in a slow month. That is the number I want you to see first.
How your plan changes the right loan
The right loan depends on the property and the plan. Buying a single rental to hold for a long time is a different question from buying a small multifamily building, refinancing a rental you already own, or pulling cash out of one property to buy another. Each path brings its own trade offs, and each is worth comparing on your actual numbers rather than on general rules. A loan that suits a long hold may be a poor match for a property you plan to improve and refinance.
Some properties or timelines do not fit a standard loan well. A property that needs significant work, or a purchase that has to close on a short schedule, may lead some investors to look at private money, usually at a higher cost and with a plan to repay or replace it. That is a separate decision, and a legal professional should review any private loan terms before you sign them.
What to bring to a first conversation
Before you talk with a mortgage professional, write down three things: what the property is and how it will be used, the rent you expect and how you arrived at it, and the cash you could put toward the purchase while still keeping funds in reserve. Rough answers are fine. They give the conversation a real starting point and keep it focused on your plan rather than on general rules. If you already own other rentals, note how each one is financed today, since that can shape the options for the next one.
Then gather the records you have: leases, rent deposits, expense records, recent tax returns and a list of any properties you already own with their loans. Your real estate agent can help with questions about the property and the purchase itself, and an insurance agent can tell you what coverage a rental needs. The financing questions can be sorted out alongside both of them, so each professional answers the part that is theirs to answer.
If you are weighing a rental purchase or refinance in San Rafael or elsewhere in California, Scott Baer can walk through how each loan option would treat the property, in plain numbers, before you commit. A background in accounting and investor relations is why Scott starts with the full picture and the plain numbers, then lets you decide. Which part of financing a rental would you like to understand first?
This article provides general information about real estate financing in California. It is not a loan offer, pre-approval, commitment to lend, or personalized legal, tax, or financial advice. Programs, availability, terms, and eligibility requirements vary by lender, property, and borrower and may change. Review the disclosures and loan documents applicable to your transaction and consult a qualified professional for tax, legal, or estate-planning guidance.
Scott Baer, Mortgage Broker and Loan Originator | NMLS #218304 | CA DRE #01103412
California Mortgage Advisors, Inc. | NMLS #1825 | CA DRE #01170868
Licensed by the California Department of Real Estate.
Equal Housing Opportunity
Written by