Investor and Multifamily Loans
What does multifamily financing need?
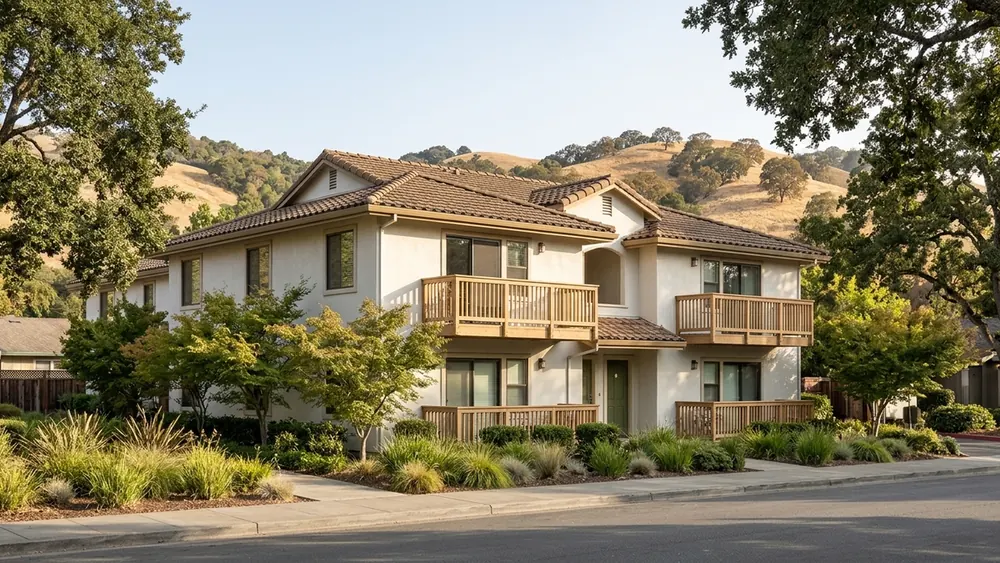
Multifamily financing looks at the building as well as the borrower. Lenders review the property’s income, expenses and condition along with your own finances, so rent rolls, expense records and a clear plan for the property matter from the start.
On this page
What multifamily lenders want to see
Multifamily financing needs two things to line up: a borrower whose finances support the loan, and a property whose income and condition support it too. Lenders review the building’s rents, expenses and physical state along with your income, credit and reserves. In practice that means rent rolls, expense records and a clear plan for the property matter as much as your own pay records do.
This matters because a multifamily purchase is partly a business decision. The building has its own income and its own costs, and the loan has to make sense for both you and the property. If you are looking at a small building in California, knowing what the review covers lets you gather the right records early and spot questions before an offer is on the table.
The details vary by program and by the size and type of property, and they change over time. That is why the useful question is not what multifamily loans require in general, but what the options in front of you would ask of this building and of you. Seeing those answers side by side makes the trade offs visible before you commit to a purchase or a refinance.
How the building’s income gets reviewed
On a multifamily loan, the building’s income is usually central. A lender typically wants to see what each unit rents for, which units are occupied and how consistently rent has been collected. The rent roll, a simple list of each unit with its occupancy, its rent and its lease dates, is often one of the first documents requested. Having a current, accurate one ready saves time later.
Expenses matter just as much as rent. Property taxes, insurance, utilities the owner pays, repairs, maintenance and any management costs all reduce what the building actually earns. Lenders often look at income after expenses, not rent alone, to judge whether the property can carry its loan. If the seller’s figures leave out costs you expect to pay, it is worth asking why before you rely on them.
Vacancy is the other piece. Units turn over, and a building rarely stays fully rented every month. Lenders often allow for that in their own way when they review income. Building your own budget with the same caution helps you see whether the purchase still works in a slower stretch, rather than only when every unit is filled and every tenant pays on time.
Where your own finances fit in
Even with steady property income, the review still looks at the borrower. Your credit, your income, your other debts and the reserves you hold after closing all remain part of the picture. If you own other properties, their loans and their income usually come into the review as well, so a complete list of what you own and what you owe helps the conversation move along without surprises.
Reserves tend to carry extra weight on multifamily property. A building can need a new roof, a plumbing repair or a stretch with an empty unit, and lenders want to know you could handle that without missing a payment. Planning for reserves early keeps the purchase from using every dollar you have, which also leaves you room to look after the property and its tenants properly.
How you hold the property can matter too. Some investors buy in their own name, and others buy through a business entity. That choice can affect the loan options, the paperwork and your personal responsibility for the debt. It is a legal and tax question first, so take it to a legal professional and a tax professional before you settle on a structure, then bring their answer to the financing conversation.
Records to gather for a multifamily loan
Because the building is part of the review, the paperwork goes beyond your own pay stubs and bank statements. Gathering these records early shows quickly whether anything needs an explanation, and it keeps you from scrambling once a purchase is under way. Not every item applies to every property, and your mortgage professional can say which matter. These are the records that come up most often.
- A current rent roll listing each unit, its rent, its occupancy and its lease dates
- Copies of the current leases for every occupied unit in the building
- Operating expense records, including taxes, insurance, utilities, repairs and management costs
- Your own income records, tax returns, bank statements and a list of your debts
If you are buying, the seller usually holds most of the property records, so your real estate agent may need to request them as part of the purchase. Ask early, and ask for records that cover a full stretch of operation rather than a single month. A snapshot can look very different from the pattern, and the pattern is what the review tends to care about most.
Who answers each multifamily question
A multifamily purchase raises questions that belong with different people. Sorting them out ahead of time keeps you from relying on a general rule that may not fit your building, and it keeps one person’s opinion from standing in for an official answer. Here is a simple way to think about who answers what before you commit to a building or a loan.
| Question | Why it matters | Who to ask |
|---|---|---|
| Which loan options fit this building | Narrows the programs worth comparing | Your mortgage professional |
| How the building’s income is counted | Shapes the loan the property can support | Your mortgage professional |
| What each loan option will cost | Lets you compare options on the same terms | Your Loan Estimate |
| The building’s condition and value | The property is part of the loan decision | A home inspector and the appraisal |
| Whether to buy through a business entity | Affects paperwork and personal responsibility for the debt | A legal professional and a tax professional |
Notice that rules of thumb and secondhand advice are not on that list. Multifamily terms change, and the only figures that apply to you are the ones attached to your own loan options. The official disclosures are where those terms appear in writing, so compare them line by line across options before you decide which path fits the building and your plan for it.
Assumptions that cause multifamily surprises
One common surprise is planning around the rent a building could earn rather than the rent it earns today. Another is trusting a seller’s expense summary that leaves out costs a new owner will carry. Both make a building look stronger on paper than it does in the review, and both can be checked early with the rent roll, the leases and a full set of expense records.
A third surprise is condition. An older building may need repairs that affect the appraisal, the loan options or the cash you need after closing. A home inspector can tell you what the building needs, and your mortgage professional can tell you whether anything found might matter for the loan. Some buyers facing major repairs look at private money for a period, usually at a higher cost.
Your next step before making an offer
Before a first conversation about financing a multifamily property, write down a few things so the discussion starts from your own plan rather than from general rules. Rough answers are fine, and your mortgage professional can tell you what else would help once you have talked it through. The point is a clear starting picture, not a finished file. It helps to have the following ready.
- What the building is, how many units it has and how they are used
- Whether you plan to hold it long term, improve it or refinance it later
- The cash you could put toward the purchase while keeping funds in reserve
- Your questions about income, expenses, reserves and how the loan options compare
With those in hand, multifamily financing becomes a set of clear comparisons rather than a guessing game. If you are weighing a building in San Rafael or elsewhere in California, Scott Baer can lay out how each loan option would treat the property and your finances, in plain numbers, with no pressure to decide. Which part of the review would you like to understand first?
This article provides general information about real estate financing in California. It is not a loan offer, pre-approval, commitment to lend, or personalized legal, tax, or financial advice. Programs, availability, terms, and eligibility requirements vary by lender, property, and borrower and may change. Review the disclosures and loan documents applicable to your transaction and consult a qualified professional for tax, legal, or estate-planning guidance.
Scott Baer, Mortgage Broker and Loan Originator | NMLS #218304 | CA DRE #01103412
California Mortgage Advisors, Inc. | NMLS #1825 | CA DRE #01170868
Licensed by the California Department of Real Estate.
Equal Housing Opportunity
Written by